Adjuster Says One Thing, Your Contractor Another. Four Ways to Settle It
When the loss adjuster's scope and your contractor's estimate disagree, the paperwork you keep decides which version survives. Four routes compared, with what each costs in time and control.
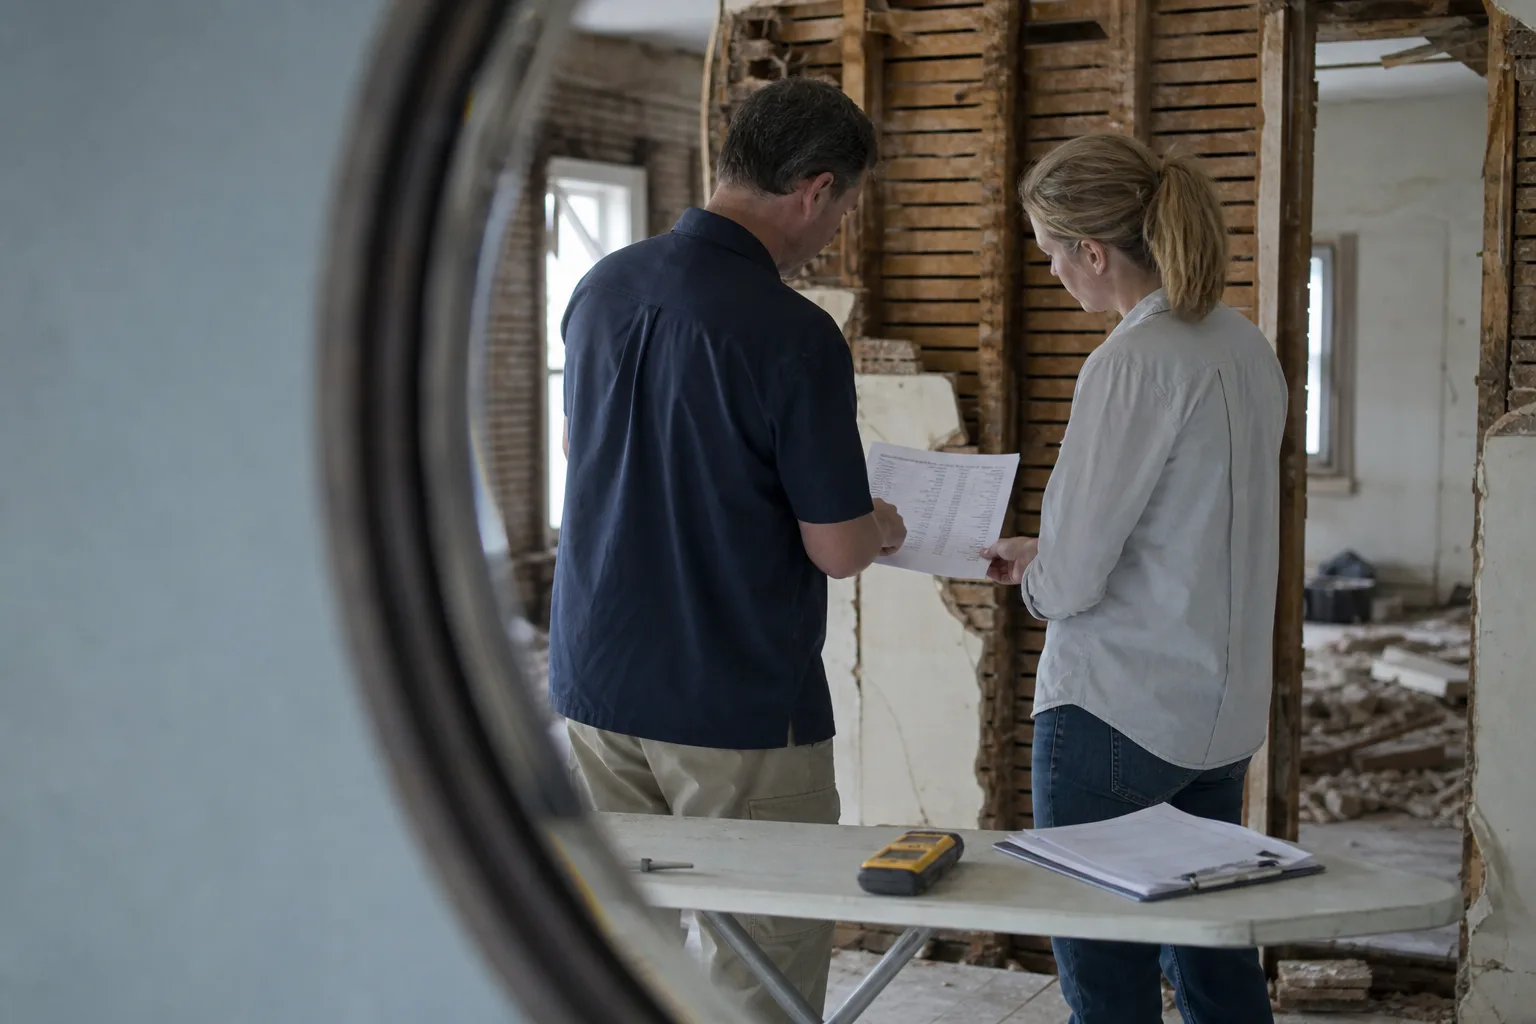
The conflict almost never arrives as a refusal. It arrives as two documents that describe the same room differently: the adjuster's scope has eighty-two line items and your contractor's estimate has one hundred and four, and the twenty-two that are missing are the ones that make the job buildable. On an old house the gap widens, because the assumptions built into a standard estimating platform were written for stud walls, drywall and vinyl, not for lath, three-coat plaster and a floor system that was never square to begin with. Sorting that out is procedural work, not a fight.
The disagreement is almost never about the total
People brace for an argument about the number at the bottom, and that is usually the last thing anyone disputes. The real disagreements are about scope, method and unit: whether a wall is repaired or replaced, whether plaster is patched or removed to the studs, whether the drying equipment stayed four days or nine, and whether the price per square foot assumes a crew that has handled lime plaster before. Each of those is a factual question with a documentary answer. Treated that way, most of them resolve without anyone raising their voice, because the file settles it.
The second common source of conflict is the policy itself rather than the building. Ordinance or law coverage, matching provisions for continuous surfaces, and the difference between actual cash value released now and replacement cost released on completion all produce numbers that look like lowballing and are in fact the contract working as written. An adjuster applying a depreciation schedule to forty-year-old shingles is not being adversarial. Knowing which category a disagreement falls into, contract or scope, tells you which of the routes below is worth your time.
Three documents that end most arguments before they start
The first is the adjuster's scope of loss, requested in writing and in full, not the summary page. Ask for the line-item export with quantities, unit prices and any depreciation applied per line. Adjusters produce this routinely and most will send it without objection. Your contractor can then respond against the same document rather than issuing a competing estimate that nobody can reconcile. Two estimates in different formats generate weeks of correspondence. One document with tracked disagreements generates a phone call, and I have watched that single request cut a month off a claim.
The second is a dated moisture and equipment log, kept by whoever is running the drying. Readings by room, taken at the same points daily, with the number of air movers and dehumidifiers and the dates they arrived and left. Restoration firms generate this as a matter of course, and homeowners who are self-managing can keep it on a clipboard. It is the only evidence that answers the most common billing dispute in water claims, which is how long equipment genuinely needed to run in a building with thick, absorptive assemblies that release moisture slowly.
The third is your declarations page with every endorsement attached, read before the first conversation rather than after the first denial. The endorsements are where the interesting language lives: the sublimit on the finished basement, the ordinance and law percentage, the roof surfacing schedule, the water damage exclusions with their carve-outs. Federal flood coverage sits separately again, under the program the Federal Emergency Management Agency oversees, with its own forms and its own proof of loss deadlines. Reading these first means you argue about things the policy will actually pay for.
Route one: reconcile the line items yourself
This is the cheapest route and, for disagreements under a few thousand dollars, usually the fastest. You take the adjuster's export and your contractor's estimate, mark every line that differs, and reduce the disagreement to a short written list with a reason attached to each entry: quantity wrong, method wrong, item missing, price assumes materials this building does not have. Send it as a supplement request with photographs referenced by number. Adjusters carry heavy caseloads and respond well to a document that lets them approve items one at a time rather than reopening the whole file.
The limit of this route is technical credibility. When the dispute turns on whether keyed plaster can be stabilized rather than demolished, or whether a heart pine floor can be sanded again, an owner's opinion carries less weight than a trade's. That is where the next route starts.
Route two: let the contractor carry the supplement
Restoration firms that work with carriers daily know the line-item vocabulary and will submit supplements on your behalf as part of the job. This costs you nothing directly, moves quickly, and works well for the mechanical questions: additional drying days, hidden damage found on demolition, subfloor discovered to be rotten. The trade-off is that the contractor's interest and yours overlap without being identical. They want the scope approved and the job closed; you may also want a code upgrade paid for, or a temporary housing allowance, or an itemization that protects your recoverable depreciation. Read every supplement before it goes out.
Route three: bring in your own estimator or public adjuster
An independent estimator produces a competing scope for a flat fee, typically a few hundred to a couple of thousand dollars depending on the size of the loss, and you keep control of the claim. A public adjuster takes over the claim entirely and works on a percentage of the settlement, with the rate set by state law in many jurisdictions and licensed by the state insurance department. The percentage applies to the whole recovery, including the part the carrier would have paid anyway, so the arithmetic favors this route on large or disputed losses and rarely on small ones. Both are worth pricing before you commit.
Route four: invoke the appraisal clause
Almost every homeowners policy contains an appraisal provision, and most people never read it. Each side names an appraiser, the two appraisers select an umpire, and their decision on the amount of the loss binds both parties. It resolves valuation disputes, not coverage disputes, which matters: appraisal cannot make a carrier cover an excluded peril. Costs are split, each side paying its own appraiser and half the umpire, and the process typically runs weeks rather than the months litigation takes. On an old building with a genuine methodology disagreement, an umpire who knows historic construction is the most efficient outcome available.
What repeats in old buildings
The same four conflicts recur: plaster repair versus replacement, matching on continuous plaster and trim runs, drying times in mass masonry and heavy timber, and code upgrades triggered when a permit opens the wall. Anticipate them, document them on day one with photographs and a written note of what the building is made of, and the adjuster becomes a person working the same file you are rather than an opponent. Most of them will tell you plainly what evidence they need to approve a line. Ask, then send exactly that.