Signing a Contingency Agreement? The Percentage Is Quoted Against Something, and You Should Know What
A contingency fee is a share of a number, and the number it is a share of is settled in the agreement you sign long before any money arrives.
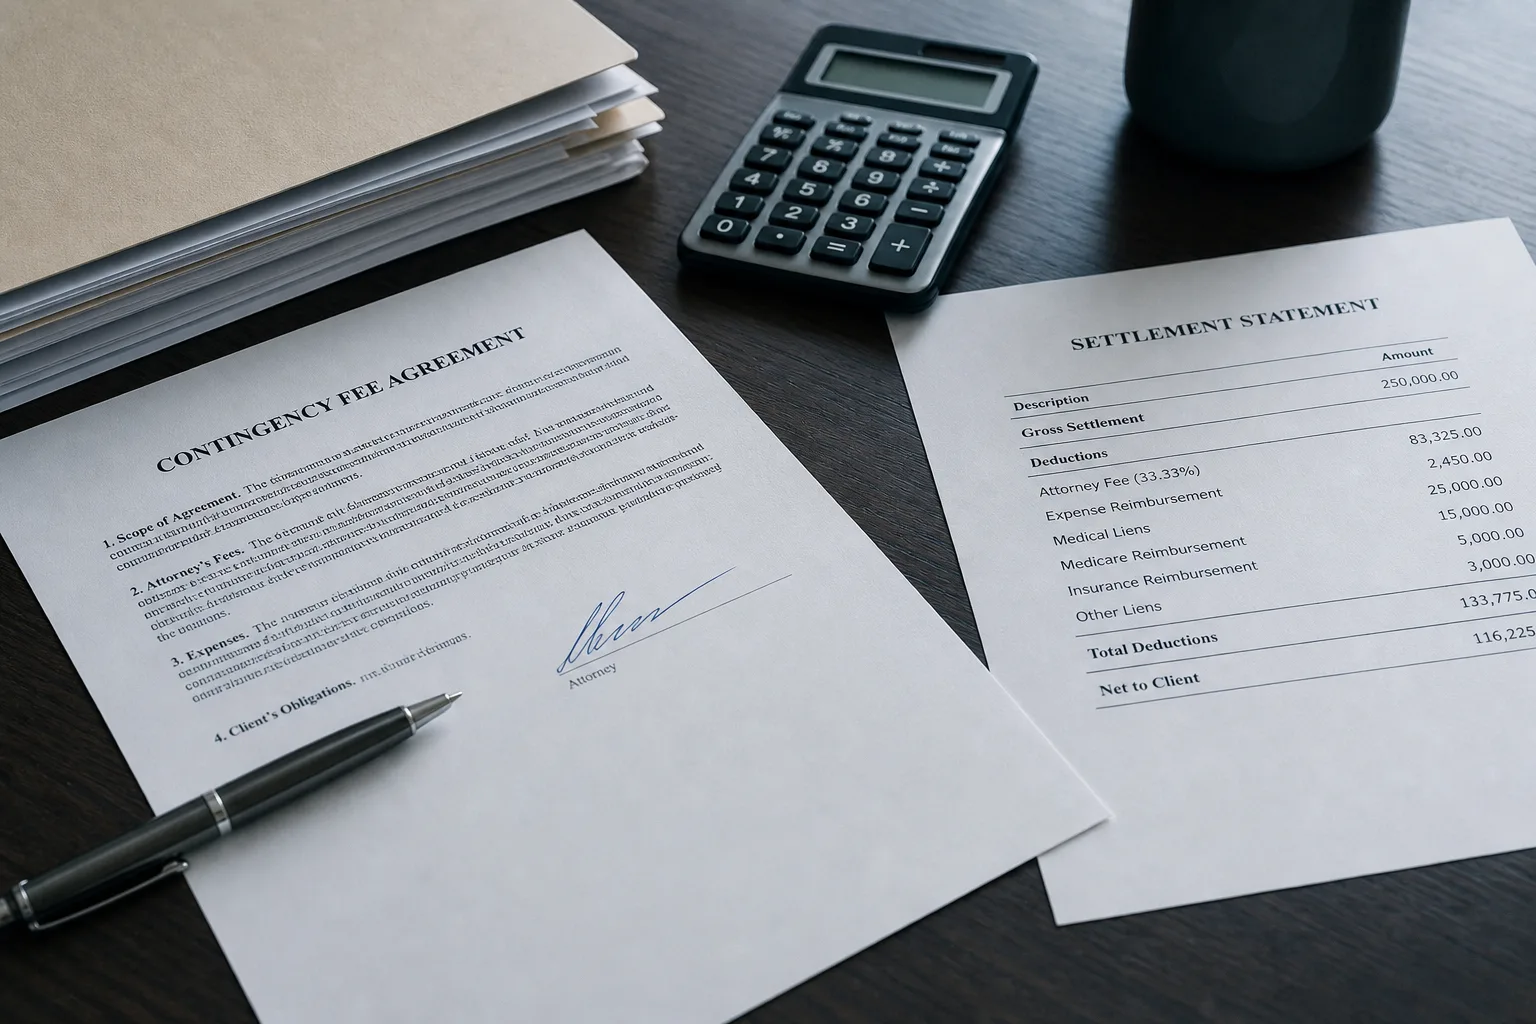
Two firms can quote the same percentage and send you home with materially different checks. The percentage is the part everyone repeats on the phone, and it is the part that tells you least, because a fee is always a share of something, and what that something is gets fixed in the written agreement rather than in the conversation. It can be the gross recovery, the recovery after case costs are deducted, or a figure that steps up if the case is filed or tried. None of those is improper. They are simply different arithmetic applied to the same injury.
Why injury work is priced this way at all
The contingency fee exists because the alternative excludes almost everyone. An hourly rate requires a client who can fund two years of depositions, medical record review, and expert fees against a defendant with no deadline and no cash flow problem. Shifting the risk onto the firm, in exchange for a share of what the firm recovers, opened those cases to people with no capital, and it also meant the lawyer had to be selective about which claims to accept. Over decades state courts responded to that arrangement by regulating it: written agreements, a signed statement of the percentage, and in some states a scale that reduces the share as the recovery grows or as the stage of the case changes.
That regulatory layer is why the paperwork reads the way it does now. The agreement is long not because the lawyer wants it to be, but because courts and bar rules require the fee, the costs, and the client's obligations to be disclosed separately rather than folded into one friendly number. The Federal Trade Commission oversees how services are advertised to consumers generally, and the effect of that broader pressure, combined with state bar discipline, has been to push the economics onto the page. The page is dull. It is also the only place the real price is stated.
Gross or net, and why the order of operations matters
Case costs are not the fee. Costs are filing fees, court reporters, medical records, investigators, and expert witnesses, and in a serious case they can run into real money. The agreement will say whether the firm advances them, whether you owe them if the case loses, and crucially whether the fee is calculated before or after they are subtracted. A one third fee on the gross recovery, with costs then taken from your remaining share, produces a smaller client check than a one third fee applied after costs come off the top. Ask which order applies and ask for an example worked on a round number, because the firm can produce one in a minute.
The party nobody asks about until the end
Somewhere behind your case sits an entity that paid your medical bills and expects to be repaid from the recovery. That may be a hospital asserting a lien under state law, a health plan asserting subrogation rights under its own plan documents, a Medicaid agency, or Medicare, and its claim is not the lawyer's fee and not the defendant's problem. It comes out of the same settlement. This is the overlooked party in the transaction, and it is the reason a client who was told to expect two thirds of the recovery sometimes receives a good deal less without anyone having misled them. Clarify early who negotiates those claims, whether the firm charges for that work, and what a realistic reduction looks like.
Lien negotiation is skilled work and it changes the outcome more than a two point difference in the headline percentage usually does. A hospital that initially demands its full billed charges can often be brought down substantially, and a self funded employer plan has more leverage than a plan governed by state insurance rules, which is a distinction worth asking about by name. Good firms treat this as part of the case and say so in the agreement. When you compare two offers, compare how each one handles the lienholder, not just the fee line, because that is where the gap between identical quotes tends to open.
How the fee structure shifts when the defendant is a national chain
Claims against large retailers follow a different path from a car collision, and the fee paperwork reflects it. A corporate defendant with in house counsel and a national defense panel does not settle early, discovery runs longer, and the proof usually turns on what the company knew about staffing, lighting, prior incidents, and security at that specific store. Firms handling, for example, Dollar Tree sexual assault attorneys work, carry those cases for long stretches with costs accruing, which is why tiered fees, stepping up if a suit is filed or a trial date is set, are common and defensible here. Ask what triggers each tier and ask whether the trigger is filing, trial setting, or a verdict, because those are not the same date.
Referral and co counsel arrangements come up in this kind of case too, and they are worth a direct question. If one firm signs you and another tries the case, the client should not pay a larger total fee because the work was divided, and the written agreement should say that the division comes out of the same percentage. Most reputable arrangements already work that way. Confirming it in writing takes one sentence and removes the only version of this that would cost you anything.
What to settle in writing before you sign
Put four things beyond argument. First, whether the percentage applies to the gross recovery or to the recovery net of costs, with a worked example at a number you choose. Second, who owes costs if the case recovers nothing, stated plainly. Third, who handles medical liens and subrogation claims, whether that work is billed separately, and what the firm's recent experience reducing them has looked like in general terms. Fourth, what event moves the fee to a higher tier, and what happens to the percentage if you discharge the firm midway. A firm that answers all four in a short email is telling you something useful about how it will communicate for the next two years.
The agreement you sign is the only document in the case that sets your own economics, and it is signed at the moment you have the least information and the most to deal with. An hour spent on the fee section, with the lienholder's claim mapped out alongside it, buys a settlement statement at the end that contains no surprises. Ask for the arithmetic on paper. Keep the copy.